
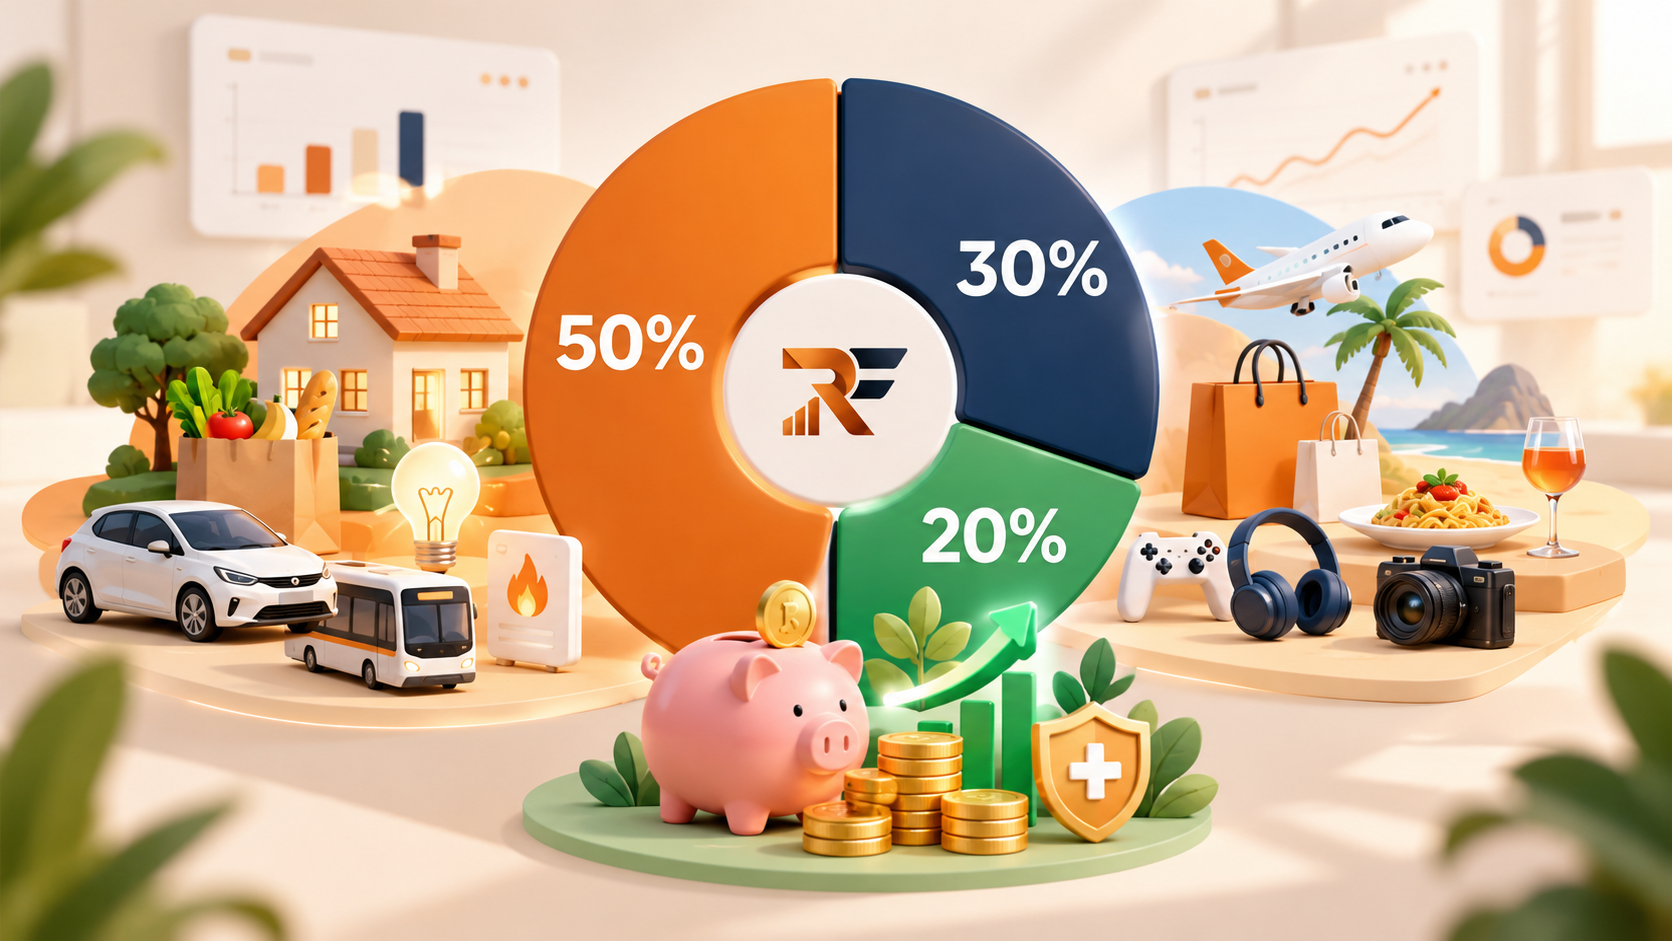
At the end of the month, do you know how much of your income paid for essentials, how much went on optional spending and how much supported future goals? The 50/30/20 budget rule offers a starting point: 50% for needs, 30% for wants and 20% for savings and some extra debt repayments. It is a guide, not an obligation or a promise that you will save. Calculate the percentages from your monthly take-home income after mandatory deductions, accounting for local tax and benefit arrangements, then compare them with what you actually spend.
What does the 50/30/20 rule mean?
The rule puts outgoing money into three broad groups. Needs (50%) are difficult to avoid: housing, essential utilities, basic groceries, necessary transport, required insurance, unavoidable healthcare and minimum required loan payments. Wants (30%) are optional or adjustable: restaurants, entertainment, shopping, holidays, comfort purchases and non-essential subscriptions. The remaining 20% is for emergency savings, a future goal, long-term investing if suitable for your circumstances, or debt repayments above the required minimum.
Classification depends on use. Internet access needed for work may be a need, while a streaming subscription is a want. Groceries can include both basic food and optional treats. The rule helps you ask useful questions without claiming that every household must categorise every purchase alike. The Consumer Financial Protection Bureau presents this split as a guideline to adapt to your situation.
How do you calculate a 50/30/20 budget?
Needs = take-home income × 0.50 · Wants = income × 0.30 · Savings and goals = income × 0.20
With €2,000 a month available after mandatory deductions, the suggested amounts are below. These are planning targets, not a statement of your actual spending.
| Group | Calculation | Amount |
|---|---|---|
| Needs | 2,000 × 50% | €1,000 |
| Wants | 2,000 × 30% | €600 |
| Savings and goals | 2,000 × 20% | €400 |
| Total | 100% | €2,000 |
A detailed example with €2,500 a month
Take a fictional €2,500 monthly take-home income. The rule gives €1,250 for needs, €750 for wants and €500 for savings and goals. The following budget adds up exactly; your own items and amounts will differ.
| Item | Amount |
|---|---|
| Housing | €800 |
| Energy and essential bills | €150 |
| Basic groceries | €200 |
| Necessary transport | €100 |
| Total needs | €1,250 |
| Item | Amount |
|---|---|
| Restaurants | €200 |
| Leisure | €150 |
| Shopping | €150 |
| Holidays and outings | €250 |
| Total wants | €750 |
| Item | Amount |
|---|---|
| Emergency savings | €200 |
| Long-term saving or investing | €150 |
| Extra debt repayment | €150 |
| Total goals | €500 |
Check: 1,250 + 750 + 500 = 2,500, and the rows in each table match their totals. The €150 extra debt repayment is separate from any mandatory minimum counted among needs. To create your own version, replace the income, then substitute amounts seen over several months. Check that each amount appears only once. RustFinance can then help you compare planned with recorded spending by category.
How does the split change with income?
| Monthly income | Needs 50% | Wants 30% | Savings 20% |
|---|---|---|---|
| €1,500 | €750 | €450 | €300 |
| €1,800 | €900 | €540 | €360 |
| €2,000 | €1,000 | €600 | €400 |
| €2,500 | €1,250 | €750 | €500 |
| €3,000 | €1,500 | €900 | €600 |
| €3,500 | €1,750 | €1,050 | €700 |
For any other income, multiply it by 0.50, 0.30 and 0.20; the three results should add back to the starting amount. This table does not mean that someone earning €1,500 can always cover their needs with €750. Housing, health and family costs can make the target unrealistic.
How should you classify spending?
Focus on necessary use versus an optional choice. Basic groceries feed the household, while treats may fit under wants. Commuting differs from a leisure trip. Required insurance is distinct from optional extra cover. A phone connection needed for work or administration may be essential; a video service may be a want. Required mortgage or loan payments go among needs, while a voluntary early repayment is a separate financial goal. Necessary treatment also differs from an optional wellness purchase.
Choose a simple rule for ambiguous items and apply it consistently across months. If a bill mixes uses, make a reasonable split or use a stable category and record the approximation. Apparently precise numbers are less useful when the definition changes every month.
How do you apply the method to real finances?
- Find take-home income. Include regular amounts you can actually use after mandatory deductions. With variable income, use a cautious estimate and review it often.
- List expenses. Examine several months of transactions, bills and due dates, including expenses that do not arrive monthly.
- Group each amount. Assign needs, wants and savings or goals. Avoid counting a savings transfer or a loan payment twice.
- Measure actual percentages. Divide each group total by income and multiply by 100. Compare these figures with 50/30/20.
- Identify workable changes. Look first for spending you can genuinely adjust. Do not cut necessary care or transport just to make a percentage look right.
- Review every month. Compare the plan with reality, explain differences and adjust next month’s targets.
A budget you can follow is more useful than a perfect-looking split that you never check. If essential costs already exceed income, start by identifying obligations and realistic options rather than forcing this rule.
What if needs exceed 50%?
Expensive housing, modest income, family responsibilities, healthcare or necessary transport may push needs to 55%, 60% or more. Splits such as 60/25/15, 60/30/10 or 70/20/10 are possible adaptations, not required standards. Each adds up to 100%. Wants or savings may need a smaller share for a time. Cover essentials and required repayments before trying to reach an artificial 20% savings target. Review the split when your income, home or household changes.
Strengths and limits of the 50/30/20 rule
| Strengths | Limits |
|---|---|
| Three groups that are easy to understand and calculate | Essential costs may exceed 50% |
| A quick view of broad spending areas | Variable income makes planning harder |
| An explicit place for savings and future goals | Categories need consistent definitions |
| A starting point for a household budget | Monthly detail and annual bills still matter |
The rule shows the broad picture but cannot tell you when a bill falls due or why one category exceeded its plan. Regular transaction checks complete the initial calculation.
How do annual expenses fit?
Annual insurance, car maintenance, holidays, gifts and school costs still belong in the budget, even when they are not monthly bills. For an expense due after a full twelve-month saving period, use:
Monthly provision = estimated annual bill ÷ 12
A necessary €600 annual insurance bill means setting aside €50 per month over twelve months. If it is due in six months and you have nothing reserved, the required provision would be €100 per month, if affordable. Money reserved for that bill remains in its spending category, here a need; it is not automatically free savings under the 20%. Holidays may instead be wants. See how to plan for large annual expenses for a fuller approach.
How can RustFinance help you use 50/30/20?
The RustFinance screenshots show accounts, categorised transactions and a Budget screen with planned, spent and remaining amounts and a monthly status for each category. They also show upcoming payments and an asset overview. The application can therefore help track the actual costs behind your three totals. There is no evidence here of an automatic 50/30/20 mode: you still need to group categories and calculate the percentages yourself.
One practical approach is to create recognisable spending categories such as “Need – housing” and “Want – restaurants”, then set monthly amounts in Budget. Add those two groups separately from money actually saved and any extra debt repayments to calculate the split outside the app. Upcoming payments can help you anticipate bills, but always verify what actually cleared. You can also calculate net worth to understand the wider effect of saving and repaying debt.
Organise a budget with RustFinance. Bring accounts together, categorise transactions and track planned versus recorded spending each month.
Estimate what you can really save
A 20% target does not tell you what your household can actually set aside. The savings capacity calculator accepts income and amounts for housing, loans, bills, food, transport, leisure and a buffer. It calculates expenses, the remaining balance and an estimated monthly saving amount, with one-, three- and five-year projections assuming a constant monthly amount. Change an input to explore a different income or cost. This is a scenario, not money already saved or a promise of returns.
Eight common mistakes and how to fix them
- Using gross pay: calculate percentages from take-home income after mandatory deductions.
- Forgetting recurring bills: review several statements for subscriptions, insurance and due dates.
- Treating every food purchase as essential: separate basic groceries from optional treats when that distinction helps.
- Calling a bill provision free savings: keep the reserved amount with the future bill’s spending category.
- Ignoring debt: count the required minimum as a need and any voluntary extra as a goal, each once.
- Missing irregular costs: spread them over the months until their actual due dates.
- Forcing 20% savings: fund essentials first and choose a sustainable target.
- Never comparing planned and actual spending: review the categories each month and adjust.
FAQ: the 50/30/20 budget rule
What is the 50/30/20 budget rule?
It is a guide that allocates take-home income to 50% needs, 30% wants and 20% savings or financial goals.
How do I calculate a 50/30/20 budget?
Multiply monthly take-home income by 0.50, 0.30 and 0.20. Then compare the results with actual spending.
How should I split a €2,000 monthly income?
If €2,000 is your take-home amount, the guide suggests €1,000 for needs, €600 for wants and €400 for savings or goals.
Does the rule work on a low income?
Not always. If essential costs exceed 50%, start with actual bills and adapt the shares without cutting needs.
Can I change the percentages?
Yes. A 60/30/10 split may fit a period of high essential costs better. Whatever split you choose should total 100%.
Do loan repayments go under 50% or 20%?
Required minimum payments are needs. Voluntary payments above that minimum can be goals. Do not count the same payment twice.
How should I include annual bills?
Estimate the bill and spread it across the months before it is due. A provision for necessary insurance remains in needs.
How is this different from a standard budget?
50/30/20 suggests three broad percentages. A detailed budget also assigns amounts to individual items and checks actual transactions.
How can software help me track the split?
Categorise transactions, set a budget per category and compare planned with spent each month. RustFinance shows those amounts in its Budget screen; an automatic 50/30/20 calculation is not established.
Make the rule fit your situation
50% needs, 30% wants, 20% savings and goals is a starting point. Adapt the shares to actual obligations, plan for future bills and review results every month. To move from a calculation to a routine, explore RustFinance, try the savings calculator or choose a download. If you are weighing a spreadsheet against an app, see Excel or personal finance software?.